India’s ₹7.86 Trillion Borrowing Plan: What It Means for Bonds, Rates and the Economy
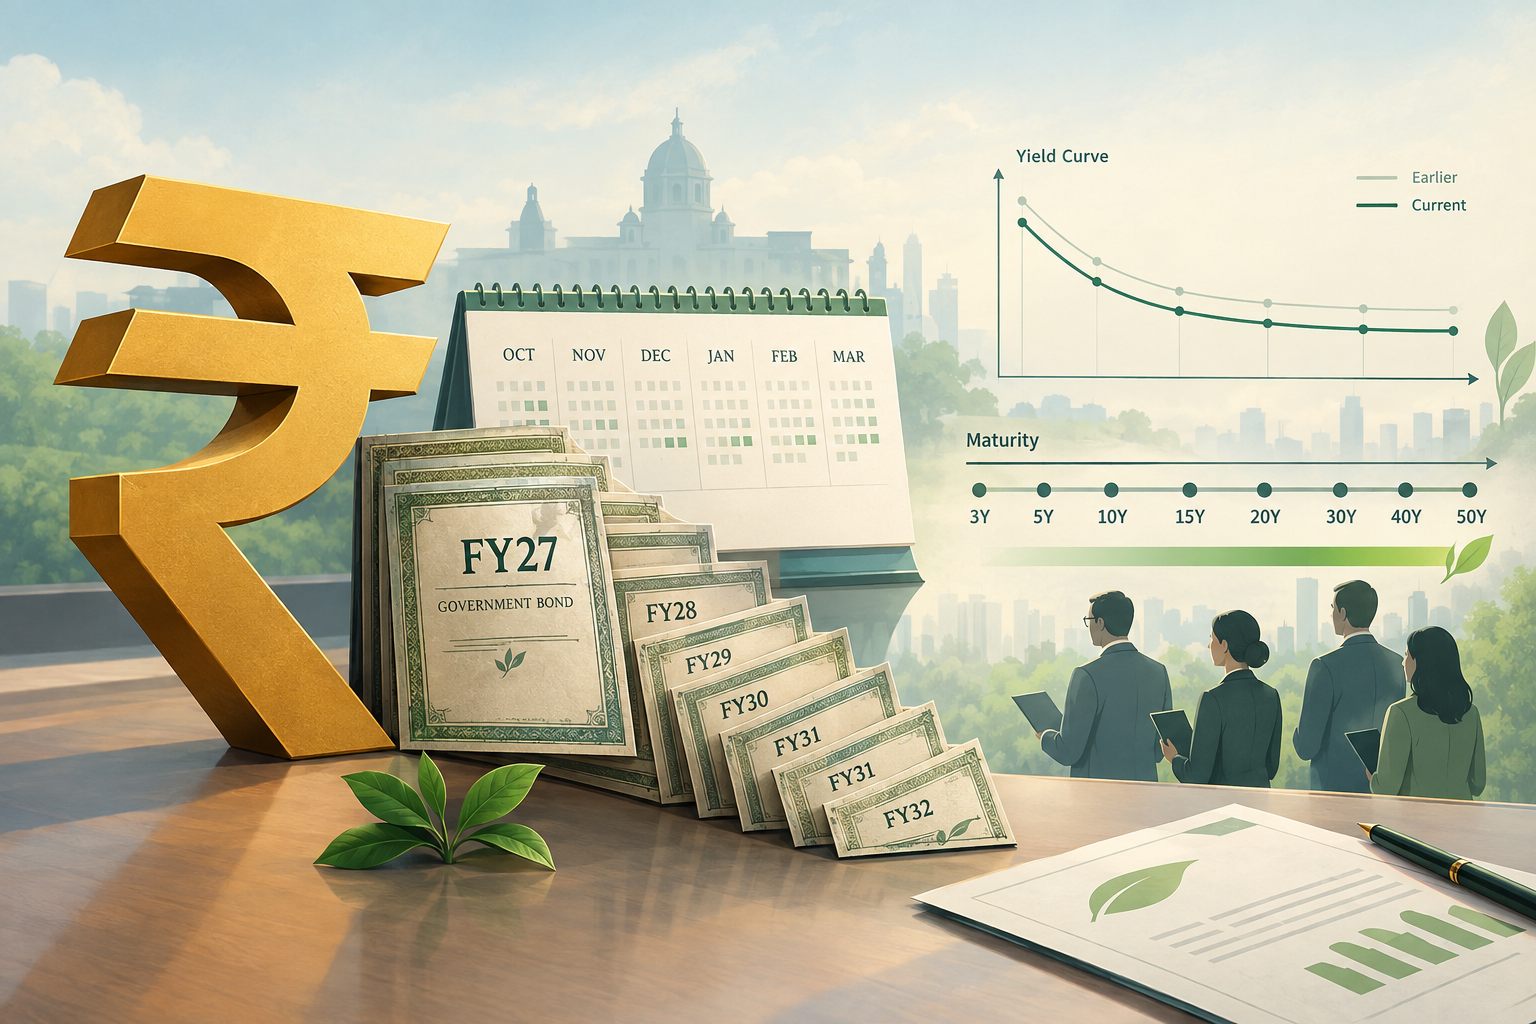
India’s government has set a gross market borrowing target of ₹7.86 trillion, or ₹7.86 lakh crore, for the October 2026-March 2027 period. The second-half calendar, announced on September 25, brings expected full-year borrowing through dated securities to about ₹15.995 trillion.
That is roughly ₹1.2 trillion below the ₹17.2 trillion projected in the Union Budget for FY27. For the bond market, the headline is encouraging: investors will have fewer new central government securities, commonly called gilts or G-secs, to absorb than originally budgeted.
However, the change requires careful interpretation. It mainly reflects debt-management operations and a lower amount of maturing debt that must be refinanced. It does not mean that the fiscal deficit itself, or the net borrowing used to finance it, has been cut by ₹1.2 trillion.
What will the government issue?
The Centre plans to complete the ₹7.86 trillion programme through 23 weekly auctions. About ₹7.71 trillion will come from conventional government securities, while ₹150 billion, or ₹15,000 crore, will be raised through sovereign green bonds. The green bonds are included in the overall total rather than being additional borrowing.
The securities will have maturities ranging from three to 50 years. Ten-year bonds will account for the largest share, but the calendar also increases the weight of longer-dated securities, including 15-year, 30-year, 40-year and 50-year bonds.
Issuing more long-term debt can increase the average maturity of the government’s borrowings. This reduces rollover risk because less debt must be repaid or refinanced in the near future. The trade-off is that investors may demand higher yields to lock up money for several decades, particularly when global interest rates are elevated or uncertain.
Why is gross borrowing lower while net borrowing is unchanged?
Gross borrowing covers both new funds required by the government and money raised to repay bonds reaching maturity. Net borrowing removes those repayments and provides a clearer picture of how much fresh market financing is being used to fund the fiscal deficit.
The government’s net market borrowing remains around the Budget estimate of ₹11.73 trillion. The lower gross figure largely follows earlier switch operations, under which near-maturity securities were exchanged for bonds maturing later. These transactions reduced the volume of repayments falling due in FY27 and therefore lowered the amount that must be raised simply to refinance old debt.
In other words, the government has rearranged part of its repayment calendar rather than announcing an equivalent reduction in its spending gap. The FY27 fiscal deficit target remains ₹16.96 trillion, or 4.3% of gross domestic product.
What could happen to bond yields?
A smaller-than-budgeted supply of new gilts is generally supportive for bond prices. When supply falls while demand remains steady, prices can rise and yields, which move in the opposite direction, can decline or face less upward pressure.
The announcement could therefore provide some relief after India’s benchmark 10-year yield closed near 7.12% on September 25. But it does not guarantee a sustained fall. Inflation, Reserve Bank of India policy, banking-system liquidity, crude oil prices, government revenue and global bond yields will continue to influence the market.
The heavier concentration of issuance at longer maturities also means the effect may differ across the yield curve. Shorter and benchmark maturities could benefit from reduced supply, while long-term yields may remain under pressure if insurers, pension funds and other large investors do not provide sufficient demand.
What does it mean for liquidity and interest rates?
Government bond auctions temporarily draw money from the financial system when investors pay for securities. Government spending subsequently returns funds to the economy. Lower issuance can reduce the amount of liquidity that auctions need to absorb, although day-to-day conditions will still depend heavily on the timing of tax collections, expenditure and RBI operations.
If gilt yields ease, borrowing costs for companies and financial institutions may also receive some support because government securities serve as reference rates across the economy. This could eventually improve conditions for corporate bonds and some loans.
Consumers should not expect an automatic reduction in home-loan or other retail rates. Those rates depend more directly on RBI policy, banks’ funding costs, deposit rates and credit demand.
How are investors affected?
Existing bondholders may benefit if yields fall because the market value of their securities would rise. Debt mutual funds with longer-duration portfolios could also gain, but they remain vulnerable to yield increases caused by inflation, global rates or heavy long-term issuance.
Investors purchasing new securities may receive slightly lower yields if reduced supply strengthens demand. Banks, insurers and pension funds will also watch the maturity mix closely, as longer bonds offer duration and predictable income but carry greater sensitivity to changing interest rates.
Why the decision matters
The revised calendar reduces refinancing pressure, limits the supply burden on the bond market and may create more room for private-sector borrowers. It also demonstrates the value of actively managing when government debt comes due.
The bigger economic signal, however, is not that India needs substantially less fresh deficit financing. It is that the government is financing the same broad requirement with a more manageable repayment schedule. Whether the improvement lasts will depend on revenue collections, expenditure discipline and financial conditions during the remainder of FY27.