Why US Treasury Yields Above 5% Are Shaking Global Markets
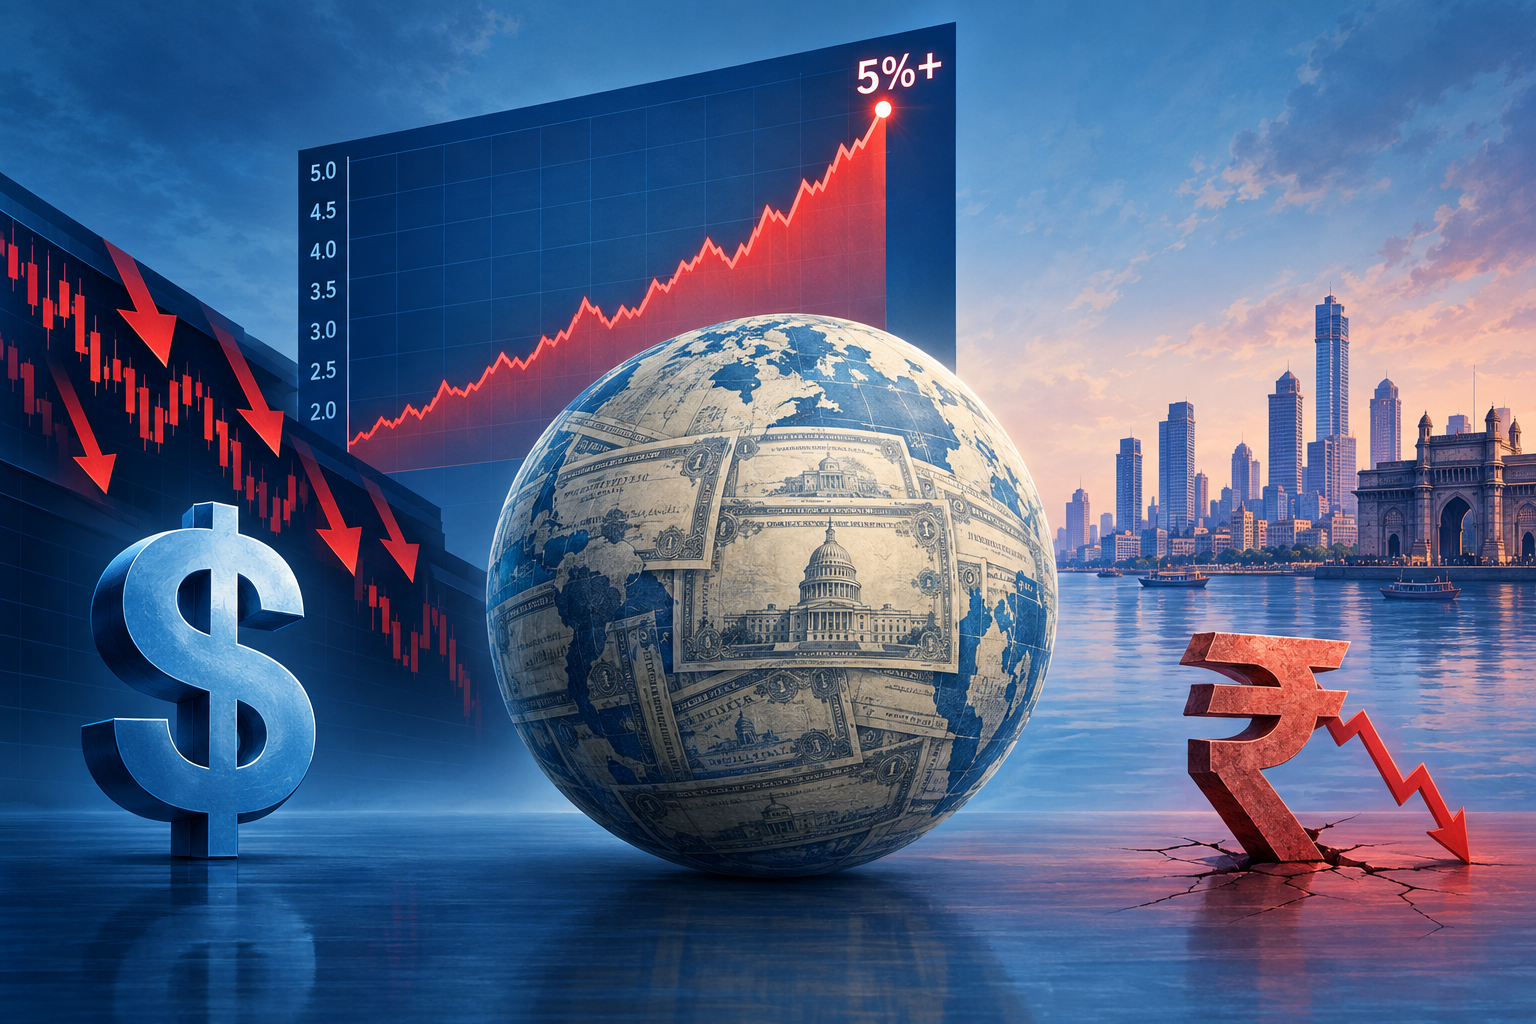
Global markets are confronting a renewed interest-rate shock after the US 30-year Treasury yield reportedly climbed as high as 5.48% and the benchmark 10-year yield reached 5.20% on September 24. Those levels, among the highest in roughly two decades, followed heavy selling across major government bond markets.
The figures are intraday yield levels rather than fixed rates for every US borrower. Bond prices and yields move in opposite directions: when investors sell existing bonds, their prices fall and the yields available to new buyers rise.
Why are yields rising?
Several concerns can push long-term yields higher at the same time. Investors may expect inflation to remain elevated, particularly when energy prices are rising. They may also conclude that central banks will keep policy rates high, or raise them further, to prevent another inflation surge.
Fiscal conditions matter as well. Governments issuing large volumes of debt must attract enough buyers. If investors become less willing to hold long-dated bonds at prevailing prices, they demand higher yields as compensation for inflation uncertainty, future interest-rate changes and the risk of expanding public debt.
A simultaneous selloff in the United States, Europe, Japan and other markets can amplify the move. Global investors often compare yields across countries and rebalance large portfolios when the relative return on government bonds changes.
Why the 10-year and 30-year yields matter
The 10-year Treasury yield is one of the financial system’s most important reference rates. It influences the pricing of mortgages, corporate bonds, infrastructure loans and other long-term credit. The 30-year yield provides a clearer view of how investors assess inflation, fiscal policy and borrowing demand over several decades.
Higher yields do not instantly reset every loan. However, if they remain elevated, governments and companies refinancing debt are likely to face higher interest expenses. Banks may also tighten lending standards or charge more for loans, affecting housing, investment and consumer demand.
How equities can come under pressure
Government bonds yielding more than 5% become stronger competitors to stocks because they offer substantial returns with comparatively lower credit risk. Some investors may shift money from equities into bonds, especially when stock valuations are already expensive.
Higher yields also reduce the present value of companies’ expected future profits. This valuation effect tends to be particularly significant for technology and other growth stocks whose earnings are projected far into the future.
Debt-heavy businesses, property companies, utilities and smaller firms can face an additional problem: rising financing costs. Banks may benefit from higher lending rates in some circumstances, but rapid bond-market moves can create losses on securities portfolios and weaken credit demand.
Borrowing costs and currencies
Persistent increases in Treasury yields can raise the cost of mortgages, corporate borrowing and US government refinancing. The impact may spread internationally because many loans and bonds are priced against US benchmarks or funded in dollars.
Higher American yields can support the dollar by making dollar-denominated assets more attractive. A stronger dollar can place pressure on emerging-market currencies and make dollar debt more expensive to service. However, the currency reaction is not automatic: concerns about US fiscal sustainability or financial instability could eventually limit the dollar’s gains.
What it means for Indian markets
India is not insulated from a global bond selloff. Higher US yields can encourage foreign investors to reduce exposure to emerging-market equities and debt, particularly when the additional return available in India no longer appears sufficient to offset currency and market risks.
Foreign outflows can weigh on the rupee and increase volatility in the Sensex and Nifty. Rate-sensitive sectors such as banks, non-bank lenders, real estate and automobiles may face pressure if domestic funding costs also rise. Highly valued technology and consumer shares can be vulnerable to the broader repricing of future earnings.
Indian government bond yields may move higher as investors demand greater returns, although domestic liquidity, inflation expectations, government borrowing and Reserve Bank of India policy will determine the scale of the reaction. A weaker rupee can also make imports such as crude oil more expensive, complicating India’s inflation outlook.
What readers should watch next
- US inflation and employment data: Strong readings could reinforce expectations of tighter monetary policy.
- Federal Reserve signals: Markets will focus on whether policymakers see the yield surge as necessary restraint or a threat to financial stability.
- Oil prices: Further gains could intensify inflation concerns and hurt energy-importing economies such as India.
- Debt auctions and investor demand: Weak demand for US or other major government bonds could produce another jump in yields.
- The dollar and rupee: A stronger dollar combined with foreign outflows would increase pressure on Indian assets.
- Indian bond yields and RBI liquidity: These will show how much of the global shock is entering domestic financial conditions.
The key issue is not simply whether a yield briefly crosses 5%. Markets will be watching how quickly yields move, how long they remain elevated and whether the selloff begins to disrupt credit availability. A gradual adjustment can be absorbed; a disorderly rise would present a much broader risk to global growth and financial markets.